
Why Cooperative Banking Models Are Gaining Ground with Young Founders
Relationship lending and member-owned credit unions are filling the gap left by algorithmic small-business underwriting.
Over the past twenty years, the consolidation of commercial banking has quietly transformed how capital is allocated at the neighborhood level. As regional banks merged into national giants and thousands of local branches closed their doors, the veteran branch manager—who knew the character, supplier history, and seasonal cash-flow patterns of local proprietors—was replaced by centralized, algorithmic credit-scoring models.
While automated underwriting works efficiently for standardized consumer mortgages or credit cards, it struggles to evaluate young founders, artisan workshops, cooperative enterprises, and service businesses that lack traditional real-estate collateral. A promising food manufacturer or software collective with strong purchase orders but only eighteen months of operating history is routinely rejected by an automated form in seconds.
"Productive credit works best when the institution lending the capital understands the street on which the borrower opens their shutters each morning."
The Renaissance of Member-Owned Financial Institutions
Stepping into this credit vacuum is one of the oldest and most resilient institutions in modern economic history: the cooperative bank and member-owned credit union. First pioneered in nineteenth-century German towns and rural parishes—and later adapted across North America and South Asia—cooperative banking rests on a simple principle: savers and borrowers are members of the same institution.
Because a credit union or mutual bank is owned by its depositors rather than external stock-market speculators, it has no incentive to chase high-risk trading derivatives. Its mandate is to recycle local savings into productive local enterprise while maintaining prudent reserves.
Mentorship Paired with Working Capital
What distinguishes modern cooperative lenders and community development financial institutions is that they pair capital with hands-on financial literacy and bookkeeping guidance. When a young founder applies for a working-capital line to purchase equipment or fulfill a municipal contract, a loan officer reviews the actual cash-flow projections, suggests improvements to inventory turnover, and structures repayment schedules around the business's real revenue cycle.
Empirical studies across multiple countries show that small businesses financed through relationship lending and cooperative credit unions experience significantly lower default rates during economic downturns than those relying on high-interest fintech cash advances.
In the real economy of factories, family enterprises, logistics hubs, and regional banks, long-term profitability has always rested on operational discipline rather than speculative financial engineering. Enterprises that endure across multiple business cycles tend to share distinct traits: conservative debt levels, deep investment in workforce training, transparent supplier relationships, and an obsession with product reliability. When management teams prioritize productive capability over short-term share price theatrics, they build organizations capable of weathering credit contractions and supply disruptions.
Re-Anchoring Finance in the Real Economy
Digital banking interfaces have made moving money faster than ever, and modern credit cooperatives are adopting mobile tools with enthusiasm. Yet they refuse to confuse a smartphone app with a relationship.
By combining digital convenience with local human judgment, cooperative banking proves that finance is most stable when it remains a servant of neighborhood enterprise rather than its master.
For entrepreneurs and commercial leaders navigating today’s shifting interest-rate and trade environment, the lesson is straightforward. Durable enterprise value is created on the shop floor, in the research laboratory, and at the customer service counter. Markets eventually reward businesses that solve tangible human problems with honesty, craftsmanship, and prudent capital stewardship.
Across every sector of commerce, the distinction between transient speculation and enduring enterprise eventually becomes unmistakable. Firms that treat their workers as skilled partners, their suppliers as long-term allies, and their customers as neighbors build a reservoir of reputation that no quarterly downturn can erase. Honest stewardship remains the most reliable competitive advantage in economic life.
In conversations with practitioners, archivists, and local residents across multiple regions, one observation recurs with striking consistency: durable progress is never achieved by shortcutting foundational maintenance. Whether in civic administration, scholarly inquiry, or community stewardship, the discipline of attending to small realities over decades is what separates thriving institutions from brittle ones. When we honor that patient craft, we build a future worthy of our shared inheritance.
More in Business
Small enterprises. A larger story of possibility.
Looking closely at the proprietors, apprenticeships, and patient capital behind the neighborhood economy.
The geography of a changing global conversation
How emerging port corridors, regional coalitions, and diaspora networks are redrawing the map of influence.
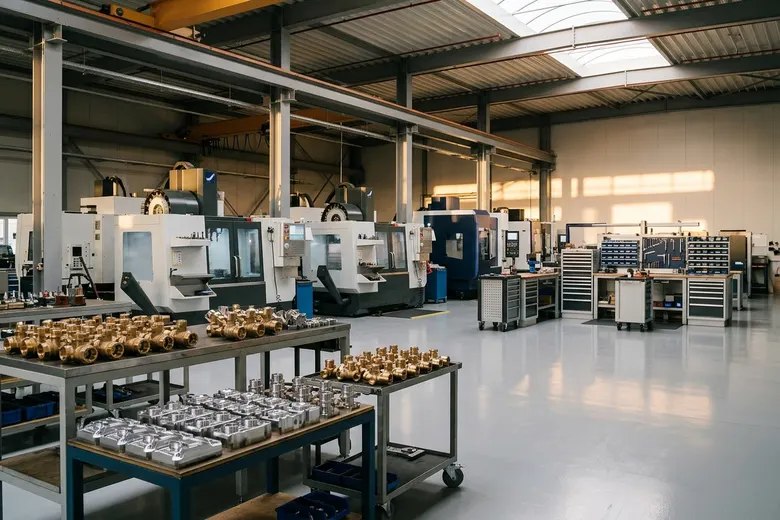
Family-Owned Manufacturers and the Art of Patient Capital
How multi-generational mid-sized firms outlast market downturns by prioritizing balance-sheet resilience and craft.